***ShareScope New Subscriber Special Offer***
Readers of my blog can enjoy a 20% first-year discount! Click here for details >>
19 September 2026
By Maynard Paton
I wrote about Headlam for ShareScope during 2020 and gave a bullish verdict:
“Headlam seems to possess the industry position, balance-sheet strength and management experience to survive this [pandemic] downturn and recover thereafter. A full share-price recovery could even offer a potential 100% gain.”
The good news?
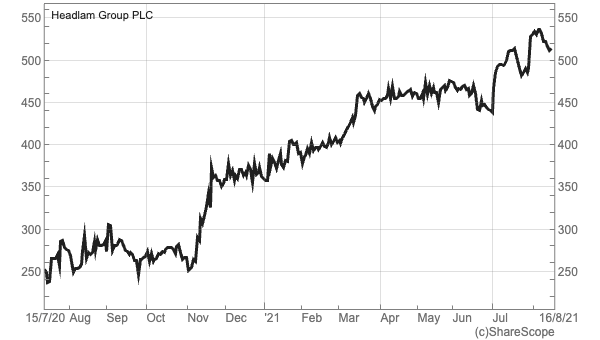
The shares went on to deliver a near-100% gain. The price reached 530p just thirteen months after my article highlighted the group’s attractions at 270p:
The bad news?
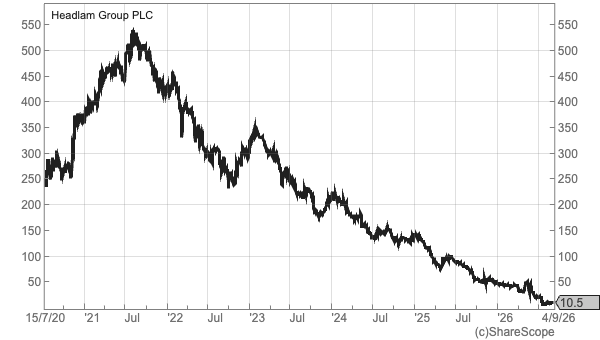
The price then slid to 10p following a catalogue of problems that culminated the other week with administrators being appointed and the shares being suspended:
Just how could “Europe’s leading floor-coverings distributor” that at the time of my 2020 review boasted…
- Industry leadership with an approximate 20% UK market share;
- Net cash of £27 million;
- A property estate valued at £80 million;
- Impressive cash generation;
- A record of paid dividends stretching back to 1992, and;
- A chief exec with almost 30 years of board service…
… deteriorate so badly to leave shareholders with nothing?
Let’s take a closer look.
Read my full HEADLAM article for ShareScope >>Maynard Paton